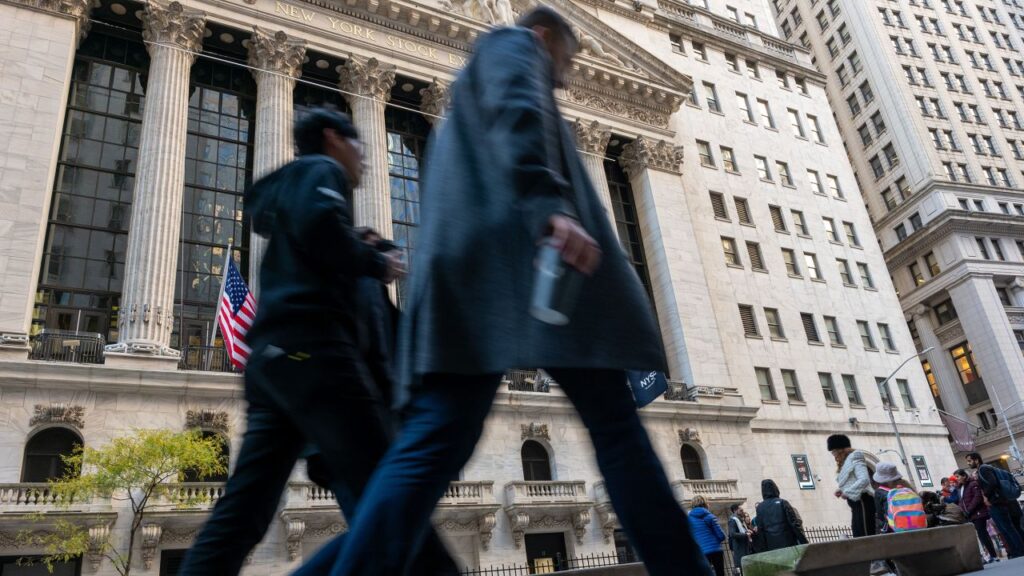
Wall Street ended last week on a firm footing after September’s employment figures pointed to a sharper cooling in the labour market than forecast. The softer data reduced the odds of a Federal Reserve rate hike this month, lifting technology shares and sending the Nasdaq to a new closing high. Over the full week, however, the picture was more mixed, as higher bond yields and energy prices continued to weigh on sentiment heading into the final quarter of the year.
US stocks rally after a weak payrolls report
US employers added only 29,000 jobs to non-farm payrolls in September, well short of the roughly 90,000 economists had pencilled in, while the unemployment rate edged up to 4.2%. The weaker reading reduced the likelihood of the Federal Reserve raising interest rates in October, and equities responded positively, with technology and mid-cap shares leading the advance.
The Nasdaq rose 1.2% to finish at a record high, the S&P 500 added 0.7% and the Dow Jones Industrial Average gained 0.5%.
The bond market reaction was less clear-cut. Treasury yields dropped sharply after the release but later climbed back, a sign that inflation, high oil prices and concerns about government borrowing remain important constraints for the bond market. Oil prices also eased on expectations that the G7 and other countries could release substantial emergency stocks, which helped support the wider market mood.
A mixed week as the final quarter begins
Friday’s gains only partly made up for losses earlier in the week, when rising bond yields and energy costs unsettled investors. Across the five sessions, the S&P 500 lost about 0.3%, the Dow dropped 1.3% and the Russell 2000 eased 0.2%, while the Nasdaq rose 0.5%.
The wider backdrop remains broadly supportive. Inflation is showing signs of moderation, consumer spending and economic activity are holding up, and corporate earnings are expected to grow strongly, with S&P 500 earnings forecast to rise by more than 30%.
Against that, valuations are elevated going into the fourth quarter, long-term yields are at their highest levels in several decades, and geopolitical and energy risks can still trigger bouts of volatility. The central question for investors is whether solid growth and earnings can keep outweighing the drag from higher interest rates and oil prices. With third quarter reporting season close, company results are likely to play a growing part in setting market direction.
Global markets at a glance
Here is how the main regions and asset classes moved going into the new week.
Asia
Asian equities advanced, led by Japan’s Nikkei 225, which rose 2.6%. Weaker US labour data dampened expectations of further Fed hikes and supported technology stocks. TSMC climbed 3%, while Hong Kong slipped 0.4%.
Lower US Treasury yields and fresh enthusiasm around AI improved risk appetite, although elevated yields and geopolitical risks remained.
US equity futures
US stock futures held steady overnight. S&P 500 and Dow futures traded close to flat, while Nasdaq 100 futures gained around 0.15%. The softer jobs figures and reduced expectations of a Fed hike continued to support sentiment, although elevated Treasury yields and oil prices kept gains in check.
Europe
European shares recovered on Friday. The STOXX 50 rose more than 1% and the STOXX 600 added over 0.5%, helped by lower bond yields and oil prices, although both indices still ended the week in negative territory.
Technology led the rebound, with ASML gaining more than 3%. Basic resources, industrials and telecommunications stocks also moved higher, supporting the broader recovery.
Currencies
The US dollar softened as the cooler jobs report reduced expectations of a Fed rate hike this month. The euro recovered from a 17-month low to trade around $1.1243, and sterling also firmed. Against the Japanese yen, the dollar eased slightly to 157.81. That said, stronger US growth and foreign demand for US assets continue to underpin the dollar.
Oil
Crude prices fell as rising exports from the Middle East and the G7’s planned release of 100 million barrels eased concerns over supply. OPEC+ left its November output targets unchanged. Meanwhile, Yemen’s Saudi-backed government launched a major offensive against the Iran-backed Houthis, adding to geopolitical risk and limiting how far crude prices could fall.
Company and sector news
Several companies saw their shares move on the back of analyst ratings, quarterly earnings or other news. The main developments are grouped below by theme.
Deals and corporate activity
Schneider Electric is reported to be nearing a deal to buy US industrial software company PTC for around $20 billion, a move that would broaden its software and digital business. An announcement could come soon, although discussions are still under way. Separately, Schneider is pursuing a €1.27 billion acquisition of Shelly Group, a Bulgarian maker of smart home equipment.
AkzoNobel has agreed to sell its decorative paints business in Southeast Asia to Nippon Paint for $1.35 billion, generating around $1 billion in net cash proceeds. The sale spans seven markets and follows earlier disposals in India and Pakistan. AkzoNobel will now turn its attention to completing its merger with US coatings company Axalta.
Paramount Skydance chief executive David Ellison said the business formed by its $110 billion acquisition of Warner Bros Discovery will be named Skydance. The deal is expected to close on 6 October, with the shares moving to the New York Stock Exchange under the ticker “SKYD”. Management is targeting $6 billion in cost savings while tackling around $80 billion of combined debt.
Citadel Securities is taking a minority stake in Wolfe Research, pairing Wolfe’s institutional equity and macro research with Citadel’s liquidity and execution capabilities. The tie-up strengthens Citadel’s offering to institutional clients and creates an alternative to traditional brokers by combining independent research with automated trading. Financial terms were not disclosed.
Energy, power and commodities
The G7 agreed to release 100 million barrels of crude oil and diesel from emergency reserves, with significant volumes of diesel to be released within 20 days. The decision follows US pressure on Europe to increase fuel supplies and avoid a possible ban on US diesel exports, as governments try to bring down sharply higher fuel prices during ongoing disruption in energy markets.
The US government is reported to be planning around $4.2 billion in financing for Vistra to raise output at no fewer than three of its four nuclear plants. The support comes as AI data centres, electrification and cryptocurrency mining push electricity demand higher. Vistra operates six reactors with more than 6.5GW of capacity, serving roughly 3.25 million homes.
Glencore lifted its 2026 profit outlook for its commodity trading division to more than $5 billion, helped by shifts in crude oil markets. The group also set out a new long-term framework pointing to trading profits of roughly $2.8 billion to $4.2 billion. Glencore shares are due to start trading in Australia on 14 October, widening its investor base.
Technology and electric vehicles
Tesla delivered 486,532 vehicles in the third quarter, ahead of expectations of 456,896. A recovery in European sales offset softer demand in the US and China, and the figures suggest the core car business may be stabilising after two years of falling sales. Production of 464,391 vehicles came in below estimates.
Elon Musk said SpaceX would be renamed “SpaceXSI”, swapping the reference to artificial intelligence for “Super Intelligence”. His comments follow a US executive order instructing federal agencies to use “Super Intelligence” and “SI” in place of “Artificial Intelligence” and “AI”. Musk did not say when the change would take effect.
Morgan Stanley has restored Nvidia as its top semiconductor pick, pointing to strong AI demand and a modest valuation of 15 times estimated 2028 earnings. The bank considers data centre construction and financing to be the main bottleneck for AI, a constraint that favours Nvidia’s wide customer base. In its view, rising earnings estimates could support the shares without the need for a higher valuation multiple.
Consumer and travel
Kering shares declined after management struck a more cautious tone ahead of its results on 22 October, reflecting softer demand for luxury goods and weaker conditions in China. Gucci showed signs of progress, while Saint Laurent and Bottega Veneta held up well. Citi lowered its price target to €243 from €282 and expects consensus forecasts to move lower.
KeyBanc upgraded Airbnb to Overweight with a $191 price target, citing resilient core growth, fast-growing hotel bookings and potential gains from AI. Hotel bookings are expanding three times faster than the homes business and could add two percentage points to room night growth. KeyBanc also views the valuation as attractive compared with peers.
Analyst views on European stocks
Morgan Stanley raised its price target on Legrand to €166 from €160, keeping its Overweight rating and top pick status. The broker pointed to stronger growth and acquisition opportunities, with data centres a key driver. Legrand expects annual organic growth of 6% to 8% between 2027 and 2030, with data centre sales rising at double-digit rates.
RBC downgraded Commerzbank to Sector Perform from Outperform and lowered its price target to €40 from €43, citing higher execution risk linked to UniCredit’s plans. UniCredit holds 49.65% of the voting rights and intends to take control from January 2027. RBC also cautioned that a possible restructuring could affect earnings, shareholder payouts and Commerzbank’s place in the DAX.
Central bank outlook
Standard Chartered now expects the European Central Bank to raise its deposit rate by 25 basis points to 2.75% in December, reversing its earlier forecast of a pause. The change follows a stronger than expected eurozone inflation reading for September, driven by energy prices, while resilient economic activity has added to expectations of further tightening.
What to watch this week
Attention this week will centre on the standoff between the US and Iran, developments in the Strait of Hormuz and the direction of government bond yields. On the data calendar, investors will be watching the US ISM Services PMI, the minutes of the latest FOMC meeting and consumer sentiment, along with German factory orders and eurozone producer prices. Releases from Japan and Australia, Canadian employment figures and inflation data from Mexico and Brazil are also due, while political developments around Brazil’s election will remain in focus.
This information is being provided solely for information purposes and should not be deemed or construed as investment advice, tax, legal, or any other ancillary regulatory advice. CCIS does not accept liability for actions, proceedings, costs, demands, expenses, damages, and losses suffered by persons as a result of information, views, or opinions appearing in this document. The financial instruments discussed are intended for retail clients however, they may not be suitable for all investors and investors must make their own informed decisions and seek their own advice regarding the appropriateness of investing in financial instruments or implementing strategies discussed herein. The value of the investment may go down as well as up and may be affected by changes in currency. Where investments are denominated in a currency other than the investor’s base or reporting currency, changes in foreign exchange rates may adversely affect the value and/or returns of the investment. Any performance figures quoted refer to the past and past performance is not a guarantee nor a reliable guide to future performance. Calamatta Cuschieri Investment Services Ltd (C13729) is licensed by the MFSA to carry out investment services business in terms of the Investment Services Act (Cap. 370). The company is a subsidiary of Calamatta Cuschieri Moneybase plc and is registered at Level 0, Ewropa Business Centre, Dun Karm Street, Birkirkara BKR 9034, Malta.