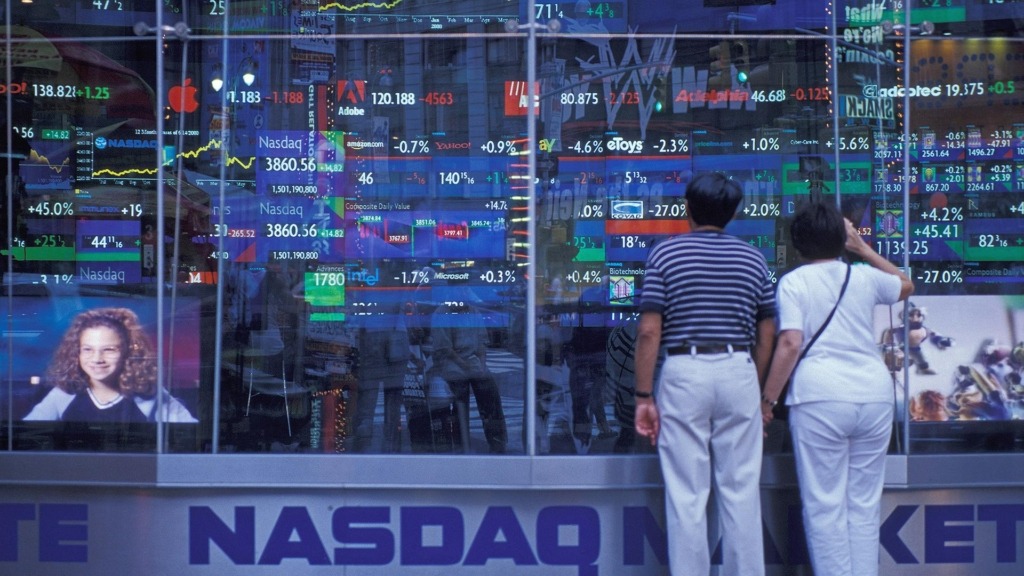
US stocks closed Friday with gains across the main indices, as a broad-based rally helped offset continued weakness among semiconductor makers. The S&P 500 added 0.6%, the Dow Jones Industrial Average climbed 0.8% and the Nasdaq 100 rose 0.5%. Global equities remained relatively resilient over a turbulent week, helped by strong company results and confidence in the underlying strength of the US economy.
Bond markets stay volatile
Bond markets continued to see significant swings, driven by high oil prices, persistent inflation and doubts over the path of monetary policy. US Treasury yields moved higher, against the direction of most other major bond markets, while the US dollar posted a fourth straight weekly gain as investors continued to favour it during a period of elevated uncertainty.
What is shaping the market outlook
Investors are balancing resilient economic growth against a number of pressures.
Earnings are increasingly supporting the bull market
The bull market that began in October 2022 is now in its fourth year. Its gains are increasingly coming from growth in company profits rather than from investors paying higher valuations. At the same time, higher energy costs, persistent inflation and rising government borrowing needs remain concerns.
Concentration in AI-linked technology stocks
A large share of market returns continues to come from a relatively small number of big technology companies, particularly those benefiting from investment in artificial intelligence. This concentration remains a key vulnerability if earnings fall short or if expectations turn less supportive.
Inflation, retail sales and bank results in focus
US inflation and retail sales figures are due this week, and the third quarter reporting season gets under way with the major banks among the first to publish results. Together, these releases should show how well consumer spending is holding up, how persistent inflation remains and whether company profits can keep supporting equities in an increasingly difficult interest rate environment.
Global markets and economic update
Asia-Pacific markets
Asian shares were mixed today. South Korean stocks fell 2.2% and Taiwanese shares slipped 0.5%, while the MSCI Asia-Pacific index excluding Japan eased 0.3%. Chinese blue chips edged 0.1% higher. Trading was subdued with Japanese markets closed, as investors assessed geopolitical tensions, uncertainty over oil supply and the approaching US earnings season.
US futures
US stock futures edged higher overnight, helped by lower oil prices after President Trump announced an energy ceasefire between Russia and Ukraine, although neither country had confirmed the deal. Investors remained cautious ahead of third quarter results, led by the large US banks, and this week’s CPI inflation data, for clues on the Federal Reserve’s interest rate outlook.
European equities
European stocks gained on Friday. The STOXX 50 rose 0.7% and the STOXX 600 added 1%, supported by lower oil prices and bond yields, easing geopolitical worries and better sentiment towards AI. Telecoms lagged after a spectrum deal by SpaceX raised fears of greater competition. Deutsche Telekom dropped 7%, Vodafone lost 3%, and Orange and Telefónica each fell 2%.
Currencies
The US dollar stayed close to an 18-month high, supported by tensions in the Middle East and demand for safe haven assets ahead of Wednesday’s US inflation release. The euro rose 0.1% to $1.121, following five consecutive weekly declines, amid concerns over France’s public finances and political uncertainty. Markets are also weighing the outlook for Federal Reserve rates.
Oil
Oil prices fell by around 1.2% this morning after President Trump announced an energy ceasefire between Russia and Ukraine, which could reduce disruption to Russian fuel supplies. The decline was limited by escalating tensions in the Middle East, including ongoing attacks on shipping in the Strait of Hormuz and clashes between Saudi Arabia and the Houthis in Yemen.
Policy and geopolitical developments
Ireland’s proposal for the 2028 to 2034 EU budget
Ireland has put forward a €1.76 trillion EU budget for the 2028 to 2034 period. The figure is 8% lower than the European Commission’s original proposal but 30% higher than the current budget. The plan cuts spending on agriculture, regional development and competitiveness. EU leaders will discuss the proposal on 15 and 16 October, amid divisions over spending priorities.
Russia and Ukraine energy ceasefire
President Trump announced that Russia and Ukraine have agreed to an immediate halt to strikes on energy infrastructure. Tensions remain, however. Trump called for President Zelenskyy to consider stepping aside, and Washington relaxed restrictions on Russian diesel exports. The diesel decision drew criticism from Kyiv and from US lawmakers, who are concerned it could help fund Moscow’s war effort.
Escalation in the Middle East
President Trump is considering fresh military strikes on Iran after deadly attacks on Riyadh airport in Saudi Arabia killed 12 people and injured more than 300. Washington is also weighing action against the Houthis in Yemen. Rising hostilities across the region and attacks on commercial shipping are increasing fears of a broader conflict in the Middle East.
Company news and share price moves
Analyst ratings, quarterly results and other news moved the share prices of several companies.
Technology and artificial intelligence
Apple has reportedly asked suppliers to reduce component orders for its iPhone 18 Pro models by 15% to 20%, amid weaker demand than expected and rising production costs. The cuts may also reflect changes to its launch timetable. Strong demand linked to AI continues to tighten global memory chip supply and push up costs for electronics makers.
Amazon is reportedly in talks to buy AI startup Decart for about $7bn, according to the Wall Street Journal. Decart builds real-time video editing technology and AI models that simulate environments for robotics and autonomous driving. The company was valued at close to $4bn in May after raising $300m.
Nvidia is reportedly discussing a larger investment in, or an acquisition of, AI startup Reflection AI, although talks are at an early stage. One option is an acqui-hire, in which Nvidia would take on the startup’s staff and license its technology without buying the whole business. Nvidia has already invested $800 million in the company.
Meta is the target of a short position disclosed by Hunterbrook Capital, which pointed to alternative data showing slower uptake of its Muse AI app. Weekly downloads dropped 8.1%, and additions to daily active users fell 62.4% from late September. Despite concerns over functionality and privacy, Meta shares declined by less than 0.3% as investors wait for third quarter results.
IBM received a Hold rating and a $240 price target as Truist Securities started coverage. The broker highlighted strength in software, mainframes and AI consulting, but flagged near-term execution risks. Recent weakness in revenue reflects software contracts being delayed as clients put AI infrastructure spending first. Analysts want to see stronger organic software growth and more contracts converting before taking a more positive view.
Healthcare
Hims & Hers shares recovered on reports that US officials may temporarily relax restrictions on certain peptides, raising hopes of a new source of growth. The company intends to launch several peptide products by the end of 2026, subject to regulatory approval. Analysts remain cautious, with pressure on earnings expectations ahead of results in November.
European deals and industrials
Siemens Energy could sell a majority stake in its steam turbines business, with banks lining up as much as €7 billion in debt financing for the deal. The division could be valued at more than €10 billion, and private equity firms including CVC, EQT and Bain Capital are considering bids. The sale would allow Siemens Energy to concentrate on power generation and grid infrastructure.
UniCredit has applied for EU antitrust clearance for its proposed takeover of Commerzbank, and a decision is due by 16 November. The Italian lender already holds close to half of Commerzbank’s share capital, while the German government keeps a 13.3% stake. Regulators can approve the deal, require concessions or open an in-depth investigation.
Rheinmetall was downgraded to Hold from Buy by Berenberg, which also lowered its price target to €1,020 from €1,600 on uncertainty over growth after 2030. Despite an order backlog of €80 billion, the broker reduced its revenue and earnings forecasts, pointing to limited contracted revenue in ammunition and vehicle systems and the need for further large contract wins.
Strategist views
Bank of America upgraded French equities to overweight and moved European equities relative to global markets up to neutral, citing their recent underperformance and limited further downside. The bank is still bearish on European shares overall and expects the Stoxx 600 to fall a further 7% by the second quarter, amid concerns over AI investment. It also downgraded software to marketweight.
The week ahead
The focus this week is on US September inflation figures, producer prices and retail sales, which will offer signals on inflation, the health of the consumer and the outlook for Federal Reserve interest rates. The third quarter earnings season also picks up pace, with results from major banks including JPMorgan, Goldman Sachs and Bank of America, as well as healthcare groups Johnson & Johnson and UnitedHealth.
This information is being provided solely for information purposes and should not be deemed or construed as investment advice, tax, legal, or any other ancillary regulatory advice. CCIS does not accept liability for actions, proceedings, costs, demands, expenses, damages, and losses suffered by persons as a result of information, views, or opinions appearing in this document. The financial instruments discussed are intended for retail clients however, they may not be suitable for all investors and investors must make their own informed decisions and seek their own advice regarding the appropriateness of investing in financial instruments or implementing strategies discussed herein. The value of the investment may go down as well as up and may be affected by changes in currency. Where investments are denominated in a currency other than the investor’s base or reporting currency, changes in foreign exchange rates may adversely affect the value and/or returns of the investment. Any performance figures quoted refer to the past and past performance is not a guarantee nor a reliable guide to future performance. Calamatta Cuschieri Investment Services Ltd (C13729) is licensed by the MFSA to carry out investment services business in terms of the Investment Services Act (Cap. 370). The company is a subsidiary of Calamatta Cuschieri Moneybase plc and is registered at Level 0, Ewropa Business Centre, Dun Karm Street, Birkirkara BKR 9034, Malta.