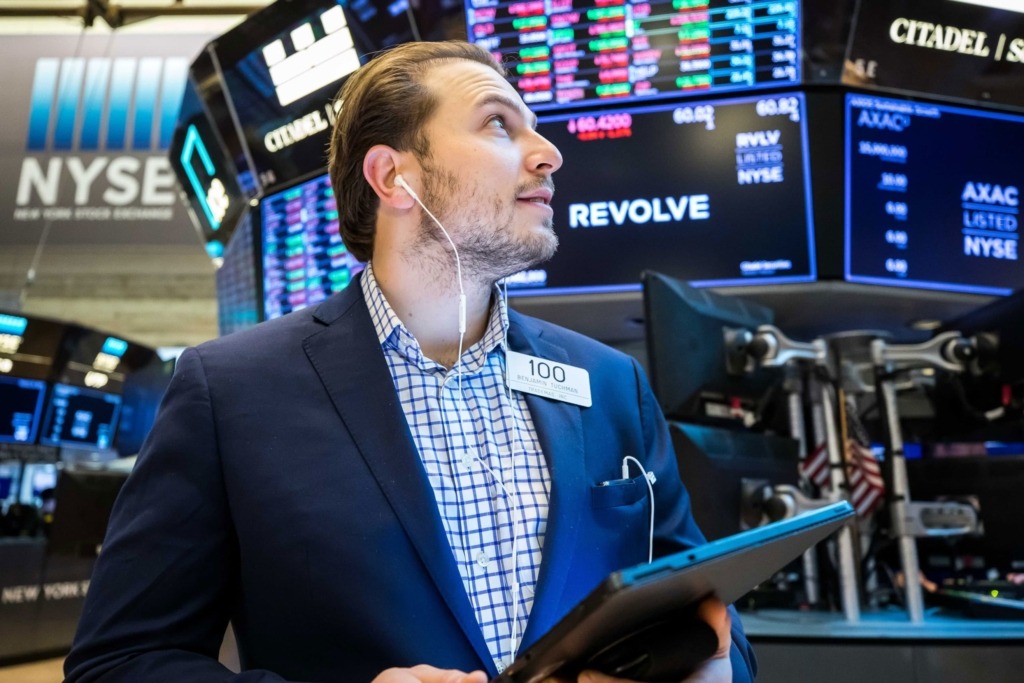
Technology stocks came under pressure on Friday amid renewed concerns over AI valuations, rising financing costs and how long earnings growth can keep pace. The S&P 500 shed 1.1%, the Nasdaq Composite dropped 2.1% and the Dow Jones Industrial Average slipped 0.3%, with technology and communication services leading the decline. Treasury yields eased as investors reduced their bets on a Federal Reserve rate hike later this month, and the US dollar softened slightly. Outside the US, the picture was more positive. European and Asian equities closed higher on the back of improving sentiment and corporate earnings, while oil prices extended their climb as supply disruptions in the Middle East continued, adding to inflationary pressures and uncertainty over the interest rate outlook.
Weekly performance and market outlook
The Nasdaq ended the week 4.5% lower and the S&P 500 lost 1.9%, the weakest weekly showing for both indices since June. The Dow Jones moved the other way, adding 0.7% as investors rotated out of technology and into more defensive sectors.
Despite the recent volatility, the broader backdrop remains supportive. Economic growth has held up, consumer spending is strong and expectations for corporate earnings remain robust. Sticky inflation, high energy prices and an uncertain path for monetary policy remain key risks. Investors are now looking ahead to results from the largest technology companies, with particular interest in what management teams say about AI investment and revenue growth, as well as the Federal Reserve decision on 28 October. While the underlying economic and corporate backdrop remains broadly supportive of equities, elevated valuations and high interest rates warrant a selective approach. Quality businesses, earnings visibility and a diversified portfolio remain key considerations.
Latest market and economic update
Asian markets
Asian equities moved lower on Monday, with worries over AI spending and technology valuations weighing on investors ahead of major earnings releases. The Nikkei in Japan fell 1.2%, South Korea lost 0.4% and Taiwan dropped 1.4%. Chinese shares recovered some of their losses after economic data came in stronger than expected, while softer oil prices and firmer bond prices provided some relief.
US equity futures
US equity futures moved higher, with Nasdaq futures up 1% as investors tentatively returned to technology names after last week’s sharp AI-driven sell-off. The S&P 500 gained 0.5% and Dow futures added 0.1%. Meta and Tesla report results this week, with AI investment costs and valuations still a concern for the market.
European markets
European equities finished Friday’s session in positive territory, helped by broad sector gains and a better outlook for corporate earnings, even as inflation concerns lingered. The Euro STOXX 50 climbed 0.6% and the STOXX Europe 600 rose 0.7%, with banks and AI infrastructure stocks leading the way. Over the week, the Euro STOXX 50 added 0.4% and the STOXX Europe 600 gained 2.0%.
Currencies
The US dollar firmed against major currencies. The euro came under pressure from political unrest in France and rising geopolitical tensions, with EUR/USD trading at 1.1242. Markets expect the Federal Reserve to keep interest rates on hold at its meeting on 27 and 28 October, with investors focused on the policy outlook and geopolitical developments.
Oil prices
Brent crude slipped 1.8% to roughly $108 a barrel, as traders priced in stronger supply after the US moved to ease sanctions and tariffs on Russian oil. Prices are still high following last week’s rally. Ongoing disruption in the Middle East, tension around the Strait of Hormuz and uncertainty over Russia-Ukraine peace talks continue to keep supply concerns alive.
China’s economy
China’s economy expanded 4.5% year-on-year in the third quarter, ahead of expectations. Industrial production and retail sales for September also came in above forecasts. Manufacturing moved back into expansion and the unemployment rate fell to 5.2%. Fixed asset investment, however, dropped 7.2%, a sign that weakness in the property sector persists.
Geopolitical developments
Russian President Vladimir Putin has suggested holding a summit next month with Donald Trump and Xi Jinping to discuss an end to the war in Ukraine, a meeting that could leave out Ukrainian President Volodymyr Zelensky. The Kremlin confirmed talks are under way, although a senior US official stated that Trump has not agreed to the meeting.
In Iran, parliament has named Mehrdad Akhlaqi Ketabchi as defence minister as tensions with the US and Israel continue. A long-serving defence industry official, he intends to rebuild military production, speed up the development of defence technology and widen cooperation with the private sector, signalling Tehran’s determination to strengthen its military capacity despite international sanctions.
Equities on the move
Several companies saw notable share price movements following analyst rating changes, quarterly results or other company news.
SoftBank
SoftBank is said to be in early discussions to buy US security services group Allied Universal, in a deal that could value the business at $18 billion, excluding debt. The transaction is not certain, but it could support SoftBank’s push into AI and robotics, complementing Allied Universal’s technology-led security services and AI-powered monitoring tools.
DeepSeek
Chinese AI start-up DeepSeek has launched an updated model, which it says delivers better benchmark results, completes tasks faster and is more cost efficient. The release adds stronger project development features and makes its Search and Fetch APIs available to all users at $0.75 per 1,000 calls, which could broaden access to low-cost AI tools.
Boeing
Boeing is close to securing FAA certification for the 737 MAX 10 after passing an important regulatory step at a meeting on Friday. Approval could arrive as soon as next week, strengthening Boeing’s position against Airbus. Certification would support higher margin deliveries, improve cash flow and help the company bring down its significant debt.
Eli Lilly
The European Medicines Agency has recommended approval for Eli Lilly’s weight loss pill Foundayo, pending review by the European Commission. The pill launched in the US in April and generated $98 million in second quarter sales, against $484.5 million for Novo Nordisk’s Wegovy pill. Foundayo’s more flexible dosing may help it compete, although take-up has been slower so far.
Schneider Electric
Schneider Electric lifted its 2026 targets for revenue and core profit growth for the second time this year, on the back of strong demand from AI data centres. Organic revenue for the third quarter grew 16.9% to €11.46 billion, ahead of forecasts. The group now expects adjusted EBITDA growth of 18% to 21%, compared with its earlier range of 14% to 19%.
Rheinmetall
Rheinmetall has reportedly taken a stake in Canadian German lithium developer Rock Tech Lithium and is investing in the Guben lithium converter project in Germany. The move comes after a C$6 million private placement announced earlier this month. The fully permitted plant is designed to produce lithium hydroxide, an essential material for electric vehicle batteries.
Besi
Besi came under pressure after SemiAnalysis reported that ASML is working on a rival hybrid bonding tool, threatening Besi’s lead in advanced chip stacking. ASML’s technology may offer better alignment accuracy and particle control, although technical hurdles remain. Competition could increase further as Korean manufacturers make progress in high bandwidth memory bonding.
Shopify
RBC Capital Markets raised its price target on Shopify to $200 from $180 and kept its Outperform rating. The bank expects growth of more than 30%, driven by resilient merchant sales, price increases and opportunities in AI-powered commerce. Shopify, which posted revenue growth of 34% in the second quarter, is due to report third quarter results on 3 November.
Skyworks Solutions
Activist investor Starboard Value believes Skyworks Solutions has substantial upside following its $22bn acquisition of Qorvo, arguing that the combined group is still undervalued. The potential upside depends on delivering at least $500m in annual cost savings within three years and operating margins of 30% to 35%, despite slowing growth and Apple’s move towards designing its own chips.
Lloyds Banking Group
RBC Capital Markets downgraded Lloyds Banking Group to sector perform from outperform and lowered its price target to 115p from 124p. Stronger competition for deposits is expected to squeeze lending margins and weigh on future profits, although structural hedge income provides support. RBC reduced its 2028 pre-tax profit forecast by 6%, but still expects Lloyds to reach its return targets.
Upcoming data and events
On Tuesday, investors will see UK labour market figures, the German ZEW sentiment survey and US housing starts. UK inflation and Japanese trade figures follow on Wednesday, US jobless claims are released on Thursday and global flash PMI surveys arrive on Friday. On the earnings side, Netflix reports on Tuesday, followed by Meta, Tesla, IBM and SAP on Wednesday, and Procter & Gamble on Thursday.
This information is being provided solely for information purposes and should not be deemed or construed as investment advice, tax, legal, or any other ancillary regulatory advice. CCIS does not accept liability for actions, proceedings, costs, demands, expenses, damages, and losses suffered by persons as a result of information, views, or opinions appearing in this document. The financial instruments discussed are intended for retail clients however, they may not be suitable for all investors and investors must make their own informed decisions and seek their own advice regarding the appropriateness of investing in financial instruments or implementing strategies discussed herein. The value of the investment may go down as well as up and may be affected by changes in currency. Where investments are denominated in a currency other than the investor’s base or reporting currency, changes in foreign exchange rates may adversely affect the value and/or returns of the investment. Any performance figures quoted refer to the past and past performance is not a guarantee nor a reliable guide to future performance. Calamatta Cuschieri Investment Services Ltd (C13729) is licensed by the MFSA to carry out investment services business in terms of the Investment Services Act (Cap. 370). The company is a subsidiary of Calamatta Cuschieri Moneybase plc and is registered at Level 0, Ewropa Business Centre, Dun Karm Street, Birkirkara BKR 9034, Malta.